Plans to Resurrect Genuine Pensions for UK Workers
New plans to resurrect genuine pensions could change how millions of private sector workers turn savings into retirement income. Announced on 3 November 2026, the proposals aim to make that process simpler. They would give savers a clearer route from a workplace pension pot to payments throughout later life.
Around 17 million private sector workers currently saving into pensions could benefit from the wider reforms. However, the announcement launches consultations on how the system should work. It does not introduce an immediate new pension payment or guarantee higher income for every saver.
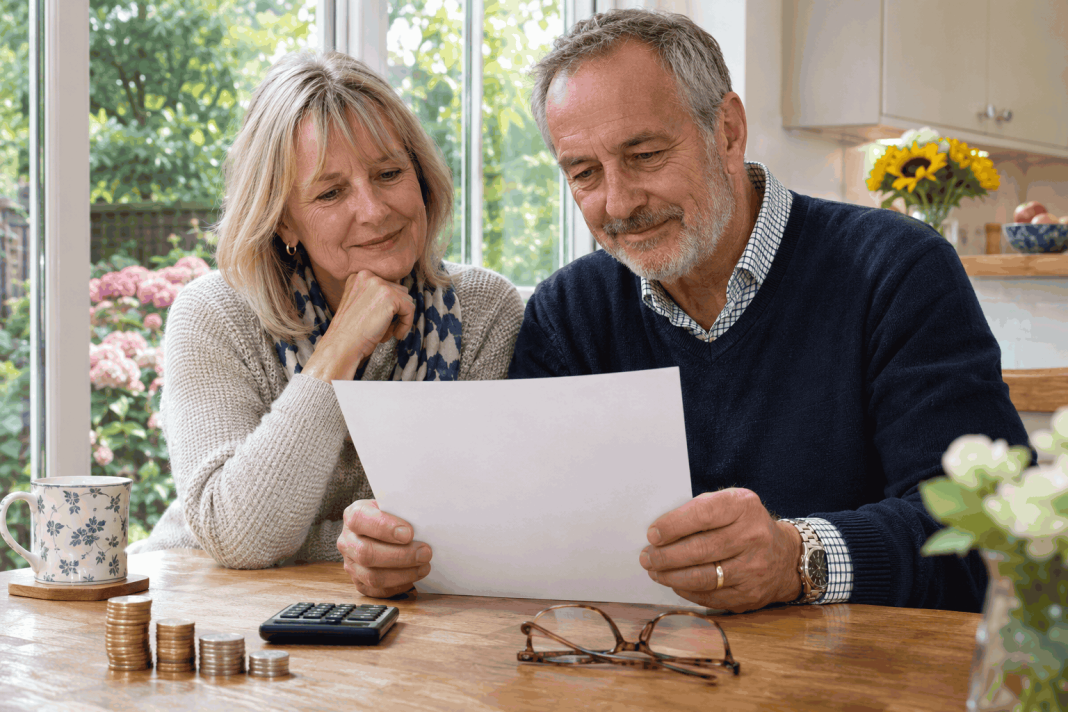
First, the proposals address a familiar problem: saving for retirement and managing retirement income require different decisions. Workers may spend decades making contributions, yet reach retirement without a clear spending plan. A structured default could help bridge that gap.
Why Resurrect Genuine Pensions for Private Sector Workers?
Traditional defined benefit pensions generally promise retirement income under scheme rules, often linked to salary and service. However, most private sector schemes of this kind have closed over recent decades. Many workers now build defined contribution savings instead.
With these arrangements, contributions and investment returns build a pot of money. That pot does not automatically explain how much someone can safely spend each year. People must consider investment performance, future spending and how long retirement might last.
Consequently, a large balance can still leave someone uncertain about their future income. Meanwhile, a smaller balance may need careful planning alongside other resources. The challenge concerns turning savings into useful payments, rather than simply displaying a pension account value.
How Plans to Resurrect Genuine Pensions Would Work
Next, guided retirement would place greater responsibility on pension providers to design or identify suitable default options. These would serve groups of savers with shared needs, rather than provide an individual financial recommendation. Workers would retain the freedom to choose another route.
The proposed framework also includes a single point of consent. A default allocation would not, by itself, start payments without the member requesting access and confirming bank details. This distinction matters for people who plan to continue working.
Readers can explore the guided retirement proposals. The central aim is to reduce difficult decisions while keeping meaningful choice. The final requirements remain subject to consultation.
Could Resurrect Genuine Pensions Plans Reduce Retirement Risks?
Furthermore, the proposals seek to address longevity risk: the possibility of living longer than savings can support. Retirement collective pensions are among the approaches under consideration. These arrangements pool resources and risks, targeting an income throughout retirement.
However, a target income should not be confused with a guaranteed payment amount. Nor should readers assume every default option will provide identical inflation protection. Comparing the actual terms will remain essential, even when the application process becomes easier.
For example, predictable income helps with household budgeting, but flexibility may matter when costs change. Someone supporting a partner may also value benefits that continue after death. These needs can lead households to prefer different arrangements.
Therefore, the practical question extends beyond the first monthly payment. Savers need to understand future changes, charges and access to their money. Clear explanations would help them assess whether an option fits their circumstances.
What Resurrect Genuine Pensions Means for Everyday Savers
For everyday workers, the strongest potential benefit is a clearer starting point. Instead of comparing unfamiliar products from scratch, members could receive an understandable retirement income option. That could make conversations with providers more focused and less intimidating.
Nevertheless, a default cannot remove every personal planning question. Housing costs, debts, dependants and other income sources can change what someone needs. A person paying rent may face different pressures from someone who owns their home.
Similarly, retirement spending rarely follows one fixed pattern. Early retirement may bring travel costs, while later years may involve greater support needs. These examples explain why simplicity and flexibility must work together.
When Resurrect Genuine Pensions Changes Could Arrive
Finally, the guided retirement consultation runs until 22 December 2026. The indicative timetable points to summer 2029 for many providers, with some arrangements following in summer 2030. These dates could change after feedback and parliamentary consideration.
Meanwhile, savers can use existing pension statements to understand what they already hold. A useful starting point is recording providers, balances, charges and any valuable benefits. Keeping this information together can make future discussions easier.
Before choosing retirement income, it also helps to compare expected household spending with available resources. Consider essential bills first, then less predictable expenses. This creates a practical basis for asking questions about any proposed option.
Professional support should reflect the individual’s circumstances, objectives and ability to absorb losses. Retirement income assessments should consider future needs, rather than focus only on today’s balance. These principles remain relevant while the new framework develops.
Providers will also need to explain their options in language members can understand. Clear examples should show what payments might cover and which decisions remain with the saver. Otherwise, a simpler process could still leave people unsure about the income they can expect.
Ultimately, plans to resurrect genuine pensions offer a promising response to a real gap in workplace pensions. Their success will depend on clear communication, reasonable costs and suitable income designs. For workers, the goal is straightforward: an easier route from years of saving to a retirement they can plan around.
I’m an Online Media & PR Strategist at BusinessFits, passionate about digital storytelling and media impact. As a journalist, blogger, and SEO specialist, I create content that connects, informs, and ranks.